Beyond Retries: Why Payments Fail and How to Recover Them
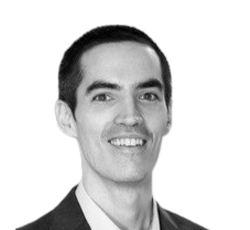
Jack Cregan
|
Founder
of
Paymend
Jack Cregan

Episode Summary
Today on the show we have Jack Cregan, Founder of Paymend, a company helping online businesses turn declined transactions into recovered revenue.
In this episode, Jack shares his experience building payment infrastructure and explains the underlying mechanics behind why payments fail, from insufficient funds and fraud detection to cross-border transactions and payment processor limitations.
We then discuss how Paymend approaches payment recovery through alternative PSPs, card monitoring, and partial authorizations, and we wrap up by exploring how businesses can reduce churn by making their products and infrastructure more embedded and difficult to replace.
Mentioned Resources
Transcription
[00:00:00] Jack Cregan: I wish people would just ask me, like, "How do I understand my failed payments or do I even have failed payments?" Most merchants don't know, and they really don't because they have a PSP. They have an integration, and they should see what's successful. I wish merchants would come and ask me, "Hey, Jack, am I suffering from this problem that we're actively promoting, that we fix?" Because a lot of merchants don't actually realize that they have it to such a significant degree.
[00:00:29] Andrew Michael: This is Churn.fm, the podcast for subscription economy pros. Each week, we hear how the world's fastest-growing companies are tackling churn and using retention to fuel their growth.
[00:00:42] VO: How do you build a habit-forming product? We crossed over that magic threshold to negative churn. You need to invest in customer success. It always comes down to retention and engagement. Completely bootstrap, profitable and growing.
[00:00:55] Andrew Michael: Strategies, tactics and ideas, brought together to help your business thrive in the subscription economy. I'm your host, Andrew Michael, and here's today's episode.
[00:01:05] Andrew Michael: Hey, Jack. Welcome to the show.
[00:01:07] Jack Cregan: Thank you, Andrew. Thanks for having me.
[00:01:09] Andrew Michael: It's great to have you. For the listeners, Jack is the founder of Paymend, helping online businesses of all sizes turn declined transactions into recovered revenue. Prior to Paymend, Jack was the co-founder and CEO of Rebills that he took from zero to exit in 24 months. So, my first question for you today, Jack, is what's the weather in Dubai?
[00:01:28] Jack Cregan: Oh, God. The weather is pretty hot. I mean, I spent the summer back home in Europe, and I've come back about two weeks ago. So, the first of September. And I mean, it's like 40 degrees. The humidity is tough. But the good thing about Dubai is it's well accommodated for this heat, air conditioning everywhere. So, most of the time I spent is, I'm actually too cold because the AC is always on. So, if I need to warm up, I'll pop outside.
[00:01:52] Andrew Michael: Yeah. It's one of those places that you like popping outside, though; you as well could also turn into a fried egg or something like that. Because I'm based in Cyprus. It gets insanely hot in the summer months. And now it's actually should be cooling down and you're still hitting 40s. I'm not even sure that is fair enough for the listeners in the U.S., but it's hot.
[00:02:11] Jack Cregan: It's super hot.
[00:02:13] Andrew Michael: And so, what's the motivation like moving away from Ireland? Obviously, you can hear the accent as well to Dubai.
[00:02:19] Jack Cregan: You know, a lot of it was I was living in rural Ireland. I hadn't really seen much of the world up until I was 24, 25 years of age, when I sold my first company. And I had a little bit of financial freedom. I was like, I may as well see something new. And Dubai is always a good place for us Europeans because there's tax advantages.
[00:02:36] Jack Cregan: It's close to home. It's easy to get to. So, I had some friends here and I said, "Hey, why not move out to Dubai?" My co-founder came with me, and it was a nice journey. I'm still here.
[00:02:45] Andrew Michael: Nice. Rural Ireland. What's that like?
[00:02:49] Jack Cregan: Rural Ireland. [crosstalk] I was from the south of a place called Limerick [crosstalk]. I'm on the border with a county called Kerry. It was a beautiful experience growing up there. And it also gave me, I kind of started my entrepreneurial journey probably around 17. So, it gave me a good six, seven years of complete focus because there was zero outside distractions in the beautiful countryside.
[00:03:11] Andrew Michael: Nice. We might be cousins. Like I found out a few years ago that both my grandparents were from Ireland, actually, from Limerick. And they both had like seven or eight brothers and sisters. So, we have a massive family, I've just almost never met over that side. It's when I need to do the heritage or something like that just to sort of figure out ...
[00:03:29] Jack Cregan: Yeah, you need to visit. You would love Ireland. I think it's beautiful.
[00:03:32] Andrew Michael: I've definitely visited a couple of times Dublin but never gone south. And I actually, it's one Dublin web summit. There was a surf summit. So, I went surfing on the west coast which was just coming from Cyprus at the time. It was insanely cold because it was in November as well. [crosstalk] Super cold. It's like, "What are these people doing?" It's like, this is not it. This is, I don't want to enjoy my day. Nice, man. And so, let's talk a little bit about payment. Maybe if you can just give us a little bit of overview of what it is you do now.
[00:04:00] Andrew Michael: Obviously, it's quite related and it's like, it almost feels like a continuation of Rebills. So, what was the origin story there? How did you decide to jump back into the next business in fintech?
[00:04:10] Jack Cregan: Yeah, quick 360, I guess, was, I was originally a drop shipper back when I was younger. And naturally, when you're shipping products outside of the US or EU from China and overseas, you have payment processing problems. Because the Stripes, Adyens, the Checkouts, etc., they want to see your fulfillment in the country generally when you're scaling up your business.
[00:04:31] Jack Cregan: So, I started to experience payment issues probably two or three years into my e-commerce journey. And that led me to learn about the acquiring industry in a whole lot of detail, or the payment processing industry. And I just got completely obsessed by it, I think. And that led me to figuring out some very complicated acquiring solutions, be it for mid-risk, high-risk businesses. And a couple of people in the network or the e-commerce network would ask me, "How are you processing your transactions? Or how are you handling transactions from Europe and the US?"
[00:05:02] Jack Cregan: And a whole series of questions that I kind of designed solutions for. And then that's what originally set up Rebills was that it was almost like an agency where we'd help medium-to-high-risk businesses get payment processing in the US and build effective routing strategies and cascading strategies to make sure they optimize approval rates. And then we started to build a lot of technology around that to support the businesses. Payment optimization, payment routing, checkout support, etc.
[00:05:29] Jack Cregan: And that business, luckily enough, scaled quite well over the two years that we had it. And then we decided that we'd take an exit just to go through that whole experience. And it was a phenomenal experience, to be honest. I learned a lot. And we sold a business after about 24 months, I think. That's where I learned the foundations for everything, payments, payment routing, etc. And then that obviously led on to payment because I see more of what's happening with our rates.
[00:05:50] Andrew Michael: Very nice. You said you had e-commerce before. Do you mind asking how old you are as well? Because I think it seems like this must have been very early in your career. [crosstalk] How old were you [crosstalk] doing the thing?
[00:06:00] Jack Cregan: I was probably 17 when I started on my e-commerce journey. I'm 27 now, so 10 years in.
[00:06:06] Andrew Michael: 10 years in. Now, so at 17 in the rural parts of Ireland, I guess, still at this stage, you decided to pick up dropshipping. Where did that come from? Where did it was like this? [crosstalk] It's probably not something people were talking about around you at the time and things like that. What made you think, [crosstalk] you know, I'm going to just go and do this thing?
[00:06:25] Jack Cregan: It's a very good question. It was just at that age, you go one of two directions in Ireland where I'm from, probably most places, is you kind of go down the party road, college road, etc. Where you kind of potentially pick the wrong path, or you maybe focus in on something. I was very ambitious as a child, and I think my goal was to be wealthy, be an entrepreneur. I realized I wasn't good at football or soccer, so potentially to build a proper income for myself and my future, I thought entrepreneurship was probably the best path.
[00:06:56] Jack Cregan: I think it was in my DNA. My dad was an entrepreneur, etc. So, it was just one morning, and I woke up, and I said, "This is what I need to do." And then I got to YouTube, and YouTube really taught me everything.
[00:07:05] Andrew Michael: Makes sense. And they pulled you in there. Cool. So, then we're talking a little bit about the payment recovery aspect today. Just before the show, you alluded to a little bit about, how payment is different to other providers and what you're doing a little bit under the hood. Obviously, I mentioned to you, "I didn't want to have another conversation about payment recovery". We've interviewed quite a few different providers and you sort of said, "No, wait, actually, we do a couple of things a little differently."
[00:07:29] Andrew Michael: And I think, actually, it might be interesting to talk through a little bit of the underlying mechanics of why payments fail. Because, to your credit, I think it is the first one where I've heard tackling this problem. Besides, maybe companies like Paddle that do it more on a wider platform, not specifically for helping you recover payments. So, maybe, if you want to share just what the secret sauces of Paymend and where you're at as a business as well. Why should people pay attention to Paymend?
[00:07:53] Jack Cregan: So, just some higher level numbers. We've, the first thing to understand about Paymend is, we take on the liability of a transaction, unlike general payment recovery strategies. So, when a merchant sends us a failed transaction, they actually send us a PAN via our API into our PCI environment. And we have a network of payment processors that we have relationships with that we actually process the payment on behalf of the merchant with our payment processors.
[00:08:18] Jack Cregan: That's probably the primary difference. So, it's almost like a merchant of record model for payment recovery. There's a couple of advantages to that when you look at the ecosystem of payment processors. Generally speaking, if a payment fails, and then you try, and recover it through a dunning flow or a retry flow, you're essentially sending that payment back to the same rail that failed us.
[00:08:36] Jack Cregan: That issuer, the customer's bank, and the payment processor, for some reason, there's some friction there if it's outside of the insufficient fund decline. And that's what we aim to tackle as step one: we get that, and we have a fresh stack of PSPs.
[00:08:49] Jack Cregan: Generally, something that most of the merchants that we work with don't have the infrastructure or resources to build out themselves. So, a network of 15 plus acquirers across North America, they might have two or they might have one. So, it's really given them a lot more optionality when they solicit a failed transaction. That's probably the primary difference with Paymend is that we open up a whole new stack of payment processors for our sub-margins.
[00:09:11] Jack Cregan: And that's proven very successful. We've scaled to 20 million in ARR. We're 40-plus people around the world two years into the journey, and we're experiencing good growth month on month. So, it's been a very exciting journey.
[00:09:22] Andrew Michael: Nice. So, just to play that back a little bit, let's say maybe a merchant's primary way of processing payments is through Stripe, and then they'll run the payment. Payment fails, and then it'll kick into something like Paymend, which then has a number of different payment processors. It may not be the primary one, but as they try to recover those failed payments, would that be a fair way to simplify the explanation?
[00:09:43] Jack Cregan: That's a perfect way to simplify. Merchant is using Stripe to process payments. Payment fails, they can route it into our infrastructure.
[00:09:52] Andrew Michael: It's true. Because I think this is definitely on the interesting side because I know as well, previously working at Hotjar, we started to see like a large volume of failed payments. And we typically found as well, and it probably comes to your experience as well as dropshipping and shipping internationally, which was, most of the time it was payments going cross-border that ended up becoming the failures. And that's banks maybe not having relationships or not accepting from certain markets or things like that.
[00:10:18] Andrew Michael: And then being able to like accept payments in their local currency and their local almost significantly improved the likelihood of that payment being processed. So, I'm interested, what are some of the main areas where you're seeing these failed payments coming from over and above cross-border payments and those relationships. What does it typically come down to?
[00:10:37] Jack Cregan: As you look at subscription payments, obviously the primary one, generally speaking, is a failure because of non-sufficient funds. And that's obviously a big problem that we're setting out to tackle, which we can cover in more detail.
[00:10:47] Jack Cregan: Other areas, I mean, the issuer suspects that the transaction is fraud based on potentially fraud data that they have on that specific merchant, because they might have had consumers that have had chargebacks in the past. And that means they tighten their screws when it relates to accepting more transactions from that type of merchant. That has a big impact on kind of false declines or do not honors, pick up cards, etc. The issuer is not fully sure on the transaction, and they're suppressing it because of the sub-merchant. Also, you have to look at the PSP stack across North America and globally.
[00:11:19] Jack Cregan: What payment processors send their transaction on behalf of the merchant? If it's a tier two processor, the likelihood of approval is far lower than what you'd see with a Stripe or Adyen, etc., because they have such strong relationships and history with the issuer banks or the customers' banks. And cross-border is obviously an obvious one. I mean, when we started a business, I was in YSL in New York, and just doing ground market research. And I was talking to the guy that was accepting card payments in the POS, and he told me every month that it was about $150,000 from customers that just don't come back because they're German cards or cards from Belgium or cards from somewhere in Europe or overseas.
[00:12:00] Jack Cregan: And I just can't get them to approve in the POS. And that was kind of right when we started the business. So really validated what we were doing and set the support in our journey. But there are some of the reasons we see NSF issuers are declining transactions because they're not sure if the merchant did not fully trusts it, and a whole series of things like that.
[00:12:16] Andrew Michael: I was actually in New York a couple of weeks here and ran into issues with my credit card trying to draw funds actually from an ATM randomly. And I assume as well, it's just because I had to walk to like five different ATMs to find one that actually ended up working. But yeah, nice.
[00:12:29] Andrew Michael: Okay. And then you mentioned as well, sort of the reason a lot of them will in the beginning just decline is because they maybe had chargebacks. And there's maybe risk that they've detected in the system. Surely, that risk then is transferred to you if they're coming over to you to try and start processing payments. And so what does that look like for you when you start working with new clients? And how do you minimize the risk that you're taking on as a business?
[00:12:54] Jack Cregan: It's a good question. And I'm very fortunate because I came from a higher risk background in our previous company. When you come from high risk, or you're any way experienced in crypto payments or gambling payments or CBD payments, you become very sophisticated very fast. You understand how to suppress fraud because you have no choice. If you don't, you don't have a payment process and a business to handle you. And you don't have a business in general.
[00:13:20] Jack Cregan: So the first thing is, we get a transaction, we're now a different merchant in the eyes of the issuer. And we have been very careful about how we've designed our payment stack since the beginning of the business to completely suppress fraud, understand our BIN-level or bank-level data on when we should take the risk in a transaction and when we shouldn't.
[00:13:38] Jack Cregan: And just because of an accumulation of them skill sets and tools that we've rolled out over the past two years, we just don't really see the issues that a merchant might see from letting too many risky transactions go through from a fraud perspective. So we've controlled that quite well.
[00:13:55] Andrew Michael: And what does it typically look like then as well? What rates of success or failure are you seeing from those different reasons? So let's say failed payments, and a company's typically seeing issues with being detected as fraudulent and payment fails, and they come over to payment that versus maybe a cross-border versus obviously insufficient funds probably being zero at this stage. Which specific issues are you more likely to be able to help with?
[00:14:19] Jack Cregan: We can help with most issues, but it also depends on the underlying payments that the merchant has. So if it's a very sophisticated merchant that we're looking at or do the partnership with, and they have five PSPs that are aggressive around when they retry with different payment processors, sometimes we need to be careful in them situations because we don't want to over try a transaction. We want to be careful with transactions in that consumer relationship. So in them cases, we'll do a deep dive in the business.
[00:14:47] Jack Cregan: We'll see what transactions are retrying. To answer your question, I guess, if it's a fraudulent relative retry, sometimes you can never retry them. For example, account closed or stolen cards, there are hard declines that Visa and MasterCard say you can never retry to understand them. So we park them once to one side so we can say there's a 0% chance of anyone recovering them. On things like do not honor, pick up card SF, etc. Generally, again, it depends on the merchant, but we can see anywhere from 8% to 12% of an uptick on decline quotes that depending on how many retries the merchant is doing under [inaudible].
[00:15:19] Jack Cregan: The cross-border stuff, because we haven't built global payment infrastructure just yet, still is a challenge for us. So for us, it's about having a relationship with an acquirer that has multi-country or multi-geo processing. And that helps us route transactions to geos or acquirers in specific geos. And the last point on NSF. NSF is something we've got quite strong with recently because the way we integrate to a merchant stack is like an async integration. So if you have a subscriber that you've exhausted retries on, you send us their transaction.
[00:15:53] Jack Cregan: We'll then register their cards with Visa and MasterCard's programs where they'll essentially monitor the card for new spend. So if you have a subscriber for 20 bucks a month, you try them reach three times, and you constantly got NSF or insufficient fund declines, you didn't register it or send it to Paymend's API. We'll register that card with the schemes on your behalf, and then we'll monitor for activity on the cards. Once we get the alert from Visa and MasterCard about the activity, then we'll rebill the user to reactivate and kind of reduce that churn level.
[00:16:26] Jack Cregan: And that's been a very efficient strategy on NSF. We also do partial authorizations. So if you say to me, "Jack, it's a $20 subscription ticket, but I'm willing to accept 12 to keep them going in their cycle." We can do a thing called a partial authorization, where when we send a $20 request to our issuers, our customers' bank, most issuers across the US will tell us what the merchant has if they don't have 20. If it follows your threshold of 12, we'll take 12, and we'll let that subscriber continue for you.
[00:16:57] Jack Cregan: So between the scheme integrations and the partial authorizations, we can get really incremental uplift for kind of subscription churn and pulling it back when it's content NSF.
[00:17:09] Andrew Michael: Very interesting. So just interesting. I wonder how many refund requests those customers are getting after thinking that it's been a couple of months now, my subscription must have been cancelled, and all of a sudden I'm getting charged for it. But at the same time, if they haven't gotten an actively cancelled subscription, you'd expect to charge for it [crosstalk].
[00:17:27] Jack Cregan: And it's important to put guardrails as well. You can't; it can't be seven months later and now we can get a partial authorization. We generally try to limit a register to 30 days. So if we get a card via your stack and you retried it over three weeks, we won't do anything after 30 days because, again, it impacts the consumer experience, and that's paramount with what we do.
[00:17:47] Andrew Michael: Nice. And the other thing then, it just reminded me of as well, was a conversation we had very early in the show with Emmerich Ernal from Aurora Pulse. And they sort of had this methodology when it came to churn and retention thinking: let's make sure that when we set targets for what we want to improve, we focus on what is within our control. And so they ended up having, let's say, 15% of churn because they were dealing with small businesses related to that actual small business going out of business. So they said, 85% of churns within our control; 15% is not.
[00:18:18] Andrew Michael: And then, to the point there's other areas where insufficient funds and these sort of things are not really anything you do from a product perspective that really is in likelihood of improving overall churn and retention. I found that really interesting because a lot of times companies say, "Okay, we want to reduce churn by like 5% this year, and we want to get to 105% NRR," but they don't really understand the underlying mechanics of it and understand what is within reach and what is with not.
[00:18:44] Andrew Michael: And so when it comes to credit card failures themselves, what would you say the ratio of percentage that you could potentially recover versus percentage that you can't based on all the different reasons that you have?
[00:18:54] Jack Cregan: Since we started a business, and this is just a very higher level number, we've recovered about 16% of the volume that has been sent into our API. To be completely transparent about that number, that removes things–again, the stuff we spoke about earlier: account close, stolen cards, etc. So it's filtering out what we can't possibly recover ever and then taking that number on that.
[00:19:16] Jack Cregan: But generally, so you understand how we come to a number when we work at a merchant is we need a business case. So we'll get their data. We'll sit with them. We'll see how many PSPs they have, how many retries they have. Assuming it's a very basic setup. They use Stripe. They don't do any retries on an initial transaction when it comes in, and they have a subscription program. On the initial, we'll generally see anywhere from like 10-11% of a recovery when they initially send us that failed one-time payment. If they're only using one PSP, if they're using two, then that number will reduce accordingly.
[00:19:49] Jack Cregan: On a subscription flow, if they're not retrying subscriptions overly aggressively, they might have two or three retries over a number of days or a number of weeks, generally we can see upwards of 15%, 16% recovery rates with our async flow, meaning they give us some time with the transaction once it comes into our payment stack. Again, that number will decrease as the merchant becomes more sophisticated and has more payment processors to retry their transactions for us.
[00:20:14] Andrew Michael: So it would be fair to say maybe roughly of all payment failures and all credit card failures, let's say, roughly 10% is recoverable. And [crosstalk] ...
[00:20:25] Jack Cregan: It's a good number.
[00:20:26] Andrew Michael: So I think it just puts things a little bit into perspective as well when you start to hear, but then as you start to grow and depending on the type of business. If you're like a very big B2C business, thousands of customers, that can really become a significant revenue driver once you're able to improve those things. And so maybe that's the next thing is, what type of customers do you typically get the most success with?
[00:20:48] Jack Cregan: It's a good question. Even though it's anti our business model, I like sophisticated merchants. So merchants that actually understand their payment stack and have control over it. By that, I mean, they're using an orchestrator, and they actually have the ability to play with when they retry transactions and plugging in multiple PSPs and building cascade profiles. But our perfect ICP fit is a merchant that's one PSP and a very limited payment stack because we've huge recovery opportunity for them. And that's merchants like big nutraceutical sellers or like brands selling skin creams or supplementation.
[00:21:24] Jack Cregan: Also, there's the other world, which is the digital world. So people selling subscriptions for their PDF products or identity intelligence or whatever the case might be. Generally, like high scale online businesses, the e-commerce, the consumer space, and also the digital space is kind of our forte.
[00:21:40] Andrew Michael: So but you said B2C typically, like do you have many B2B clients? [crosstalk] We described there was a predominantly B2C and high volume.
[00:21:50] Jack Cregan: Everything's high volume B2C.
[00:21:54] Andrew Michael: So I think that also then makes a lot more sense in terms of the price point you're talking about earlier and reasons for failure. And so it becomes a lot more effective when you're dealing in those sorts of volumes, specifically in those price points as well. So I'm actually keen, I always ask a few questions. I just want to be aware of the time here as well. But what's one thing that you know today that you wish you knew when you got started with your career when it comes to churn and retention?
[00:22:19] Jack Cregan: I probably think like that a lot of churn is defensible. Most merchants don't realize that you can build sophisticated cancel flows. You can have an optimized payment stack. You can have a slightly better product with a slightly different tweak. And I think that if I was to go back and watch all the churn that I've experienced over my career, it's that exact point. Is that you can deflect a significant portion of churn and increase retention by being smart with your business model and your operations. Everything from payments to messaging to cancellation flows. That's probably what I would have kind of adopted if I was to start over again.
[00:22:57] Andrew Michael: But let's talk about this, because we touched on briefly at the beginning of the call, was that basically, you have not experienced a whole lot of churn in your own businesses, in real estate or payment. And the main reason, as you alluded to, is you become critical infrastructure to a business. So once you get put in, it's quite difficult to move. The switching costs are high. Was it a deliberate decision when you got started, or just happened to be like a happy accident that you're in? "Oh, well, like actually churn and retention that plagues 99% of SaaS businesses is not really for us."
[00:23:28] Jack Cregan: It's a good question. I think I always like sophisticated problems. So problems that require really sticky solutions that require a lot of investigation and time to figure out and build a product around.
[00:23:37] Jack Cregan: Because I always seen a moat in businesses like that. And that naturally led to very good retention and very little churn from the offset because we became so embedded in such a critical part of someone's infrastructure. We had their payment infrastructure, recovery infrastructure, and our payment. And that was always my mantra for businesses. Let me just build something really sophisticated that no one really wants to leave.
[00:24:01] Andrew Michael: Makes sense. I think one of the things at my time during Hotjar chatting to David Dominant, the CEO, was he had this budget lists check, which was if the things go terribly bad in the economy, like tanks, and CFOs will start to pressure everyone around, what tools do we have? What do we keep? What do we don't keep? How far are you up on the budget list? Are you the first one to go or the last one to go? And so you try to understand how critical you were.
[00:24:26] Andrew Michael: And then typically, what you ended up finding out is infrastructure sort of products and those that were critical to the functioning, or whether it's payments or people or whatever [inaudible] last one of the list to go. And then your market tech stack, and you had a whole bunch of other peripherals sitting at the top, that's going to be the first. And so that's also from my lens, trying to think when I do something next as well, "Okay, where on the budget list would this specific product service lie? How ingrained is it to the core infrastructure of the business?"
[00:24:56] Andrew Michael: Just because I think churn retention is one of those things that has the ability to crush businesses. It was the premise of the show and having an advantage where you're operating in a space where like to your point, maybe the product needs to be a little bit more sophisticated, go to market and be able to make a dent. It has a huge upside on the other end where once you get in, you're in.
[00:25:15] Andrew Michael: But I think once you like to get in is probably also quite a bit more difficult. So I don't know, what does that look like for you, from a go-to-market strategy perspective for Paymend? How are you acquiring customers yourself? And what is that sort of deal cycle length look like? I mean, how long does it take for you to acquire a new customer in this space?
[00:25:34] Jack Cregan: What you've made there is a very good point. Like, the CFO has forced the budget, what does he got first? And ideally, yeah, being at the bottom of that list is preferential. Go to market to be completely transparent is a tricky one. Ticker than I've ever had it before as payment has continued to grow. And our deal sizes and accounts have turned into more enterprise accounts. It's been a whole learning experience that I've kind of fallen short on and really had to bring in external advisory resources and sales resources to help with.
[00:26:02] Jack Cregan: Because now it's a process, so that might take three to six months to get fully integrated into a sophisticated enterprise merchant payment stack. There's a lot of holes that you need to jump through, legal battles, etc. But they tend to be quite rewarding once you get through them. And one deal like that can change the trajectory of your business forever, arguably.
[00:26:20] Jack Cregan: So it's been a process that I've learned a lot on, and it's kind of changed the function of our business. We've had to become a lot more operational and strategic and legal over the past 12 months as we changed trajectory around the business model that we wanted to work with. But it's a long, tedious sales cycle of integrations, business cases, multiple meetings with different stakeholders between legal, Paymend operations, and leadership to get the deal over the line.
[00:26:46] Jack Cregan: And for us, it's all about demonstrating how we can improve retention, reduce churn on the payment side. And we're pretty successful doing that with our stage to go to market or sales approach so far.
[00:26:57] Andrew Michael: Very nice. I think that was going to be my assumption as well. Exactly what you laid out is like that's what you're typically in a finding. But then once you're able to close a deal and you have them as customers, they can have huge significant impact on the overall bottom line. And like you say, you end up then keeping them for a long time just because it is a critical function of the business.
[00:27:15] Andrew Michael: And also you probably face less like the graduation churn effect, which is something we saw in a couple of other businesses where you have a solution that meets the needs of a customer at a certain stage in their growth and trajectory. And then eventually they grow up and they become bigger and they start to build their own and stuff. I think this is still probably one of those problems that would be last on the list to tackle out of all the problems companies have to say, "Okay, let's actually go and rebuild the stack now that Paymend has so we can manage this process."
[00:27:15] Andrew Michael: I think fortunately that position, but obviously at some point it scales to a significant size and we're like, "Okay, we need to maybe bring this in house now as well." So that will probably be in my mind like the other that or businesses going out of business, which is something not in your control would be the two main areas.
[00:27:58] Andrew Michael: So maybe another question then is obviously you deal with payment processing a lot and failed payments and stuff. What's one question you wish more people would ask you when it came to failed payments, but they don't.
[00:28:10] Jack Cregan: I mean, the question I'd first, I wish people would just ask me, "How do I understand my failed payments or do I even have failed payments?" Most merchants don't know. And they really don't because they have a PSP, they have an integration and they just see what's successful. I wish merchants would come and ask me, "Hey, Jack, am I suffering from this problem that we're actively promoting, that we fix?" Because a lot of merchants don't actually realize that they have it to such a significant degree.
[00:28:34] Jack Cregan: And that's what I would love merchants to ask me. From a churn perspective, "Hey, how can we reduce churn via Paymend?" And I mean, there's an incredible route to do that. And with all the tools that exist now.
[00:28:46] Andrew Michael: And you don't have like a lead magnet on your site to interconnect with Stripe and tell them how much they're suffering or not. [crosstalk]
[00:28:52] Jack Cregan: You know, maybe that's good advice. And we might need to restructure our funnel on websites.
[00:28:59] Andrew Michael: Nice. Well, Jack, I mean, it's been an absolute pleasure chatting with you today. Is there any sort of final thoughts you want to leave with the listeners with? Any piece of advice you have for a wrap up?
[00:29:06] Jack Cregan: I think just build a sticky product that you don't have to think about churn with, you know, and that's probably all I could say. Try to make it sophisticated and do everything you can to keep that retention.
[00:29:17] Andrew Michael: Everyone's busy listening. I was like, screw this guy. I'm coming to the show because I have an issue with churn and the product already. He's in the right space. But, no, I definitely, I think it's being delivered at the start for me is a key thing. But unfortunately, I think most people aren't thinking about churn and retention at the start. They're thinking about growth. They're thinking about building a business.
[00:29:37] Andrew Michael: And then churn and retention becomes this thing at some point where they someone decides, "Okay, let's calculate where our growth ceiling looks like. When do we stop growing? When do we start getting into trouble?" And then sometimes, "Holy shit, it's like we're here already. We need to figure this out now. We have years to go." And so I think that's the unfortunate thing is it's often when people realize that it's too late and then they sort of get into this panic mode. But some survive it, and others don't.
[00:30:01] Jack Cregan: One thing just to lead on again is when we sign a customer, I obsess about the first 60 days to such a fine degree. Every single day I'm getting reports on our new signed merchants, previous 30 days, 60 days [inaudible]. Because that's the critical metric for us is, "How is our performance in the first 60 days?" And if there's anything that's off track based on the targets that we've set for that customer for 60 days, then it's an investigation every time to see how can we put it back on track. Maybe that could be some advice for anyone listening to, is that the first 30, 60, 90 days is critical to that process for the consumer in the LTV.
[00:30:39] Andrew Michael: I love that piece of advice, Jack. I'm sure you're going to go on to do amazing things in the future. I wish you best of luck now with payment. And for the listeners, everything we discussed today, you'll be able to find that in the show notes. We'll leave links to it so you can pick up there. And is there any sort of way that people can give up to you at your work, Jack? Are you available anywhere online, anywhere you recommend they follow?
[00:30:57] Jack Cregan: Yeah, I've got pretty active on LinkedIn. That's probably a great place to catch me, just Jack Cregan on LinkedIn. And you'll see some updates. Feel free to ping me a message or whatever. I'm quite responsive there. And that's probably the best place for just sending me an email.
[00:31:09] Andrew Michael: Cool. Well, thanks very much. We'll make sure again to leave that in the show notes. Appreciate your time today, Jack. And wish you the best of luck going forward.
[00:31:14] Jack Cregan: Thank you, Andrew. You too. Talk soon.
[00:31:16] Andrew Michael: Cheers. And that's a wrap for the show today with me, Andrew Michael. I really hope you enjoyed it and you're able to pull out something valuable for your business. To keep up to date with churn.fm and be notified about new episodes, blog posts, and more, subscribe to our mailing list by visiting churn.fm. Also, don't forget to subscribe to our show on iTunes, Google Play, or wherever you listen to your podcasts.
[00:31:44] Andrew Michael: If you have any feedback, good or bad, I would love to hear from you. And you can provide your blunt, direct feedback by sending it to Andrew at churn.fm. Lastly, but most importantly, if you enjoyed this episode, please share it and leave a review, as it really helps get the word out and grow the community. Thanks again for listening. See you again next week.
Comments
Jack Cregan
A new episode every week
We’ll send you one episode every Wednesday from a subscription economy pro with insights to help you grow.
About
The show
My name is Andrew Michael and I started CHURN.FM, as I was tired of hearing stories about some magical silver bullet that solved churn for company X.
In this podcast, you will hear from founders and subscription economy pros working in product, marketing, customer success, support, and operations roles across different stages of company growth, who are taking a systematic approach to increase retention and engagement within their organizations.
Related
Listen To Next


Robbie Kellman Baxter

EP
61
How to cement trust with new customers in times of a crisis and uncertainty


Rav Dhaliwal